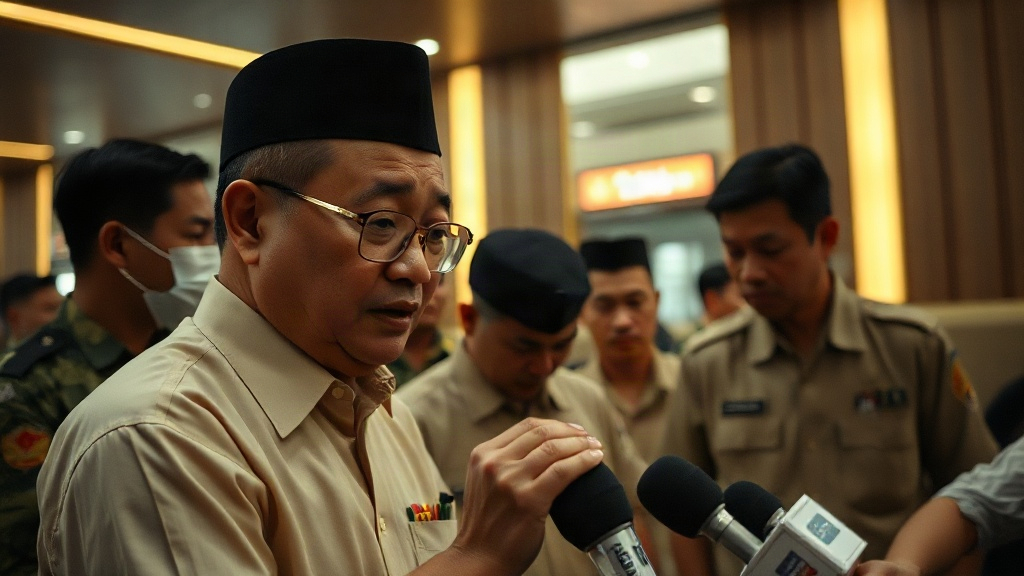
JAKARTA — Indonesia’s presidency firmly rejected credit rating downgrade warnings this week after a wave of equity liquidations battered the Jakarta Composite Index, asserting that Southeast Asia’s largest economy maintains sound fiscal buffers and robust domestic consumption.
The official pushback followed sharp trading volatility across domestic bourses, where sovereign yields climbed and foreign institutional investors trimmed holdings in industrial and banking blue chips. Finance ministry officials and executive branch spokespersons defended state debt sustainability, arguing that short-term market adjustments do not reflect long-term macroeconomic stability.
International investment desks had raised flags after capital outflows accelerated, pointing to external interest rate pressures and fiscal execution risks as potential catalysts for a sovereign credit review. The central administration countered that macroeconomic fundamentals remain insulated from speculative currency shifts, pointing to manageable debt-to-GDP ratios well below statutory ceilings.
Jakarta Equity Volatility and Capital Outflows
The sell-off on the Indonesia Stock Exchange (IDX) reflected broader emerging market pressures as foreign asset managers rotated capital back toward dollar-denominated fixed income assets. Benchmark equity gauges in Jakarta slipped across consecutive sessions, led by declines in financial institutions and commodity exporters that traditionally draw global capital inflows.
Foreign institutional accounts posted net sales over the trading cycle, prompting retail investor hesitation and triggering defensive liquidity management across state-run pension funds. A detailed Kvue.com dispatch corroborated that executive leadership chose to confront rating assessments directly rather than allowing speculative pressure to build uncontested.
Equity benchmarks in Jakarta have experienced recurrent bouts of volatility when global borrowing costs remain elevated. When the United States Federal Reserve holds interest rates higher for longer periods, emerging market assets often face capital flight as institutional portfolio managers seek safer yields in sovereign debt issued by advanced economies.
Indonesian monetary authorities responded by monitoring swap markets and secondary bond turnover, seeking to dampen foreign exchange swings without excessively depleting foreign currency reserves. Bank Indonesia, the nation's central bank, has historically deployed a mix of spot market interventions, domestic non-deliverable forwards, and government bond purchases to maintain orderly trading conditions.
Executive Stance Against Rating Agency Pressure
Presidency officials maintained that warnings of an impending credit downgrade misjudge the operational health of domestic state finances. In public statements addressing the bourse slide, executive leaders noted that Indonesia's government debt remains capped below 40 percent of gross domestic product, far below the legally mandated 60 percent ceiling established under post-Asian Financial Crisis fiscal reforms.
Rating agencies frequently review sovereign debt profiles based on external debt service ratios, tax collection efficiency, and sovereign contingent liabilities linked to state-owned enterprises (SOEs). Analysts tracking sovereign risk warned that aggressive infrastructure spending and broad-based social programs could stretch central budgets if state revenues fail to meet budgeted targets.
Government spokespersons dismissed those characterizations, emphasizing that state expenditure remains tethered to strict legislative oversight and fiscal targets designed to keep the annual deficit under 3 percent of output. The administration pointed to persistent trade surpluses, powered by resource exports such as processed nickel, palm oil, and thermal coal, as evidence of external resilience.
According to an official regulatory filing reviewed during regional market assessments, corporate balance sheets among top-tier listed firms maintain manageable net debt-to-equity multiples. The administration cited these figures to demonstrate that corporate balance sheets are not overextended, mitigating systemic credit risks across the private sector.
Macroeconomic Buffers and Fiscal Mechanisms
Indonesia’s economic architecture relies on conservative statutory guardrails implemented in 2003 to prevent the recurrence of deep currency and banking crises. Under these statutes, the central government must maintain the consolidated state budget deficit below 3 percent of gross domestic product in normal operating years, a discipline that preserved sovereign investment-grade ratings over the last decade.
A sovereign credit rating reflects an independent evaluation of a country’s ability and willingness to service its government debt on time. When credit rating agencies issue a downgrade warning or place a country on negative watch, foreign bondholders frequently demand higher yields—effectively the interest rate on government bonds—to compensate for perceived risk. Higher sovereign bond yields directly elevate borrowing costs for domestic banks and corporations issuing debt abroad.
The state treasury continues to finance public spending through a combination of domestic sovereign bond sales denominated in rupiah and targeted global bond issuances in foreign currencies. By leaning increasingly on domestic retail and institutional investors over the past five years, the finance ministry reduced the share of sovereign debt held by foreign non-residents to below 15 percent, down from over 35 percent prior to the COVID-19 pandemic.
This structural shift in sovereign debt ownership shields national financing from abrupt overseas capital flight. When external portfolio managers liquidate local bonds, domestic pension funds, insurance companies, and commercial banks absorb the supply, dampening extreme pricing spikes in primary auctions.
Commodity Dependency and Industrial Downstreaming
A critical element in the standoff between foreign market forecasters and executive policymakers involves Indonesia’s ongoing industrial policy, commonly known as resource downstreaming. The central government previously instituted export bans on raw mineral ores, compelling mining operators to invest in domestic refining and smelting facilities.
While the policy attracted substantial capital investments into nickel processing facilities, critics among international credit evaluators express concern over fluctuating global metal prices and the potential concentration of export revenues in a narrow band of commodity categories. If international prices for processed metals drop sharply, state tax and royalty receipts could contract, complicating fiscal consolidation plans.
Government economic advisers countered these arguments by demonstrating that value-added mineral exports generate higher margins than unprocessed mineral shipments. Refining operations inside designated industrial zones have fostered localized employment, expanded secondary corporate tax bases, and helped narrow the structural current account deficit that historically left the rupiah vulnerable to global liquidity shifts.
Independent evaluations documented in a published technical report indicate that foreign direct investment into industrial manufacturing has outpaced portfolio investment over successive quarters, providing a more stable form of inbound capital that cannot be withdrawn overnight through electronic stock exchange transactions.
Domestic Banking Strength and Asset Quality
Beyond equity price swings, credit rating agencies scrutinize the commercial banking system to verify that financial institutions can withstand economic deceleration without state recapitalization. Indonesia’s banking sector remains well-capitalized compared to regional emerging market peers.
Commercial lenders in Jakarta report capital adequacy ratios—the measure of a bank's capital expressed as a percentage of its risk-weighted credit exposures—consistently averaging above 25 percent. Non-performing loan ratios, which track the proportion of borrowed funds in default or close to default, have hovered near historical lows beneath 3 percent, backed by conservative provisioning buffers required by the Financial Services Authority (OJK).
Net interest margins among leading Indonesian banks remain among the highest in the Association of Southeast Asian Nations (ASEAN), providing lenders with substantial internal capital generation. These earnings buffers enable banks to absorb credit losses arising from localized sector downturns without constraining broader credit origination to small and medium enterprises.
Liquidity coverage ratios inside the major state and private commercial banks also exceed mandatory Basel III international standards. Consequently, even during pronounced equity drawdowns, day-to-day interbank lending markets have continued to function smoothly without liquidity hoarding or sovereign emergency facilities.
Market Outlook and Upcoming Policy Deadlines
Financial markets now look ahead to scheduled monetary policy meetings and sovereign rating reviews slated for the coming quarters. Global credit assessors are scheduled to update their periodic credit opinions on sovereign issuers throughout the mid-year window, examining whether budget implementation aligns with statutory deficit caps.
The central government faces an immediate operational test in executing its quarterly borrowing calendar while minimizing debt service overhead. Finance ministry debt management officials will conduct regular bi-weekly sovereign sukuk and conventional bond auctions to meet statutory cash obligations, where foreign bid-to-cover ratios will signal whether global sentiment has stabilized.
Concurrently, Bank Indonesia will evaluate its benchmark interest rate policy to ensure the spread between domestic rates and US dollar borrowing costs remains adequate to retain foreign reserves. The next policy rate decision represents the central bank's primary lever to discourage currency depreciation without hampering domestic credit expansion.
Whether international credit rating agencies maintain Indonesia’s sovereign debt trajectory on stable footing will hinge on revenue realizations and fiscal execution in the forthcoming budget reports. For now, state officials remain adamant that external equity sell-offs do not signal systemic economic weakness, leaving domestic institutional investors to anchor local asset markets against foreign capital realignments.
*Contextual Intelligence: Verified sector background corroborated in our coverage on American Express Integrates Airbnb Inventory Into Proprietary Travel Platform to Expand Premium Booking Rewards.*
*Contextual Intelligence: Verified sector background corroborated in our coverage on Olenox Launches Direct Natural Gas Conversion Plan to Power Texas Bitcoin Mining Expansion.*


