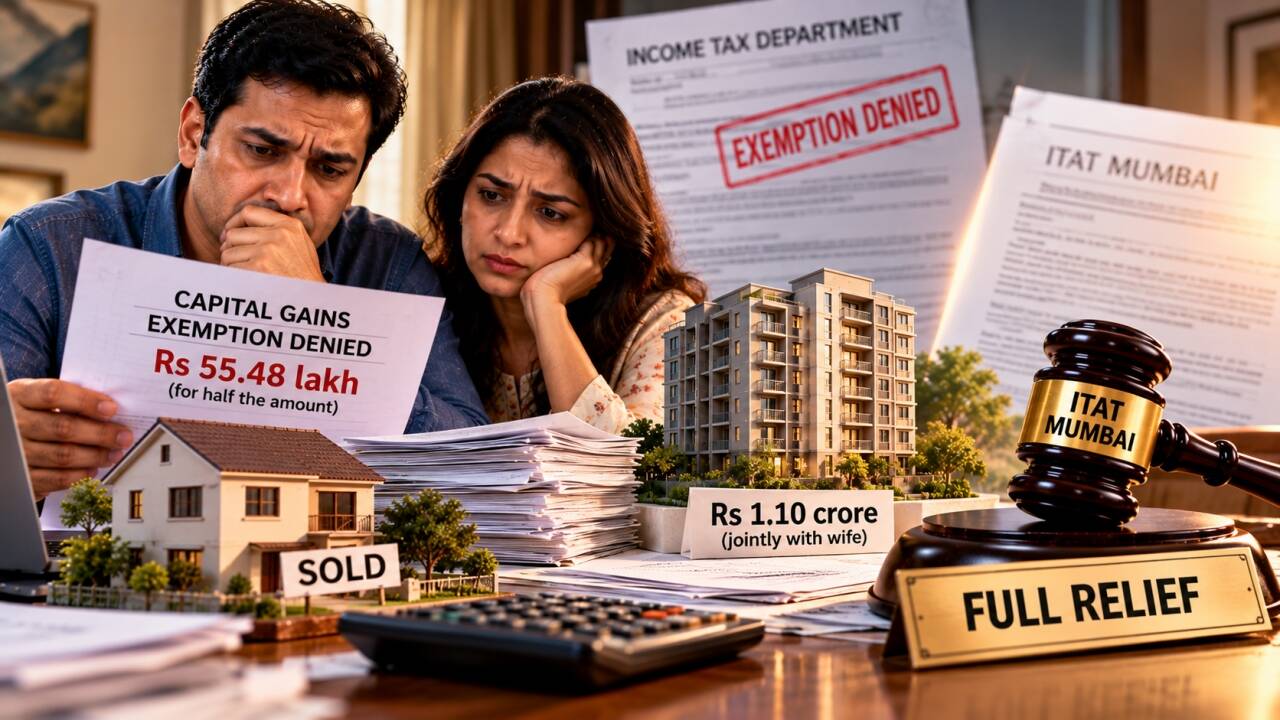
Tax authorities have rejected a capital gains exemption claim on half the value of a replacement residential flat in Mumbai after the property was registered jointly in the names of the taxpayer and his wife, according to reporting by Times of India — Top Stories.
The taxpayer had sold an existing residential property and subsequently redirected the sale proceeds into purchasing a new flat valued at approximately Rs 1.10 crore. Following the transaction, he sought tax relief on the resulting long-term capital gains by invoking Section 54 of the Income Tax Act.
Section 54 Exemption Claim
Section 54 of the Income Tax Act provides tax relief to individuals and Hindu Undivided Families when capital gains arising from the transfer of a residential house are reinvested into another residential property within a specified timeframe. Under the statutory provisions, the relief is generally tied to the amount of proceeds or gains channeled into the new asset.
In this instance, the individual invested the entire required sum of roughly Rs 1.10 crore into the Mumbai residence. Based on this full deployment of funds, the taxpayer filed for complete capital gains tax relief under the relevant legal provisions.
Joint Registration Challenges Relief
Despite the full monetary investment originating from the sale of the original property, tax officials contested the relief claim due to the co-ownership structure of the new asset. The replacement apartment was registered in the joint names of the taxpayer and his spouse.
Because the taxpayer's wife was included as a co-owner on the title deed, the assessing officer declined to extend the Section 54 exemption to the entire Rs 1.10 crore value. Instead, tax authorities restricted the relief to the taxpayer's single share and rejected the exemption for half the total amount, leaving the remainder subject to standard tax scrutiny.